Who owns West Campus student housing?
Six properties show how student lease obligations become property cash flow—and why rent levels cannot identify an owner’s return.
In this guide
A student sees an installment. The owner sees a year of contracted rent. A lender sees the cash remaining after operations and the claims ahead of it. West Campus makes these different views easy to confuse, especially when an expensive bed sits in a building whose common equity earns very little.
At the July study cutoff, Callaway’s $1,959 advertised installment meant $19,590 paid in ten parts before parking and required liability coverage. Meals, furniture, utilities, internet, housekeeping and amenities were included. The sample’s highest modeled effective gross income also carries its lowest NOI margin because those services cost money. SkyLoft has another problem: claims below the property’s NOI leave little for common equity. At 26 West, an older acquisition basis drives the largest modeled return.
The common mechanism is a calendar. Students sign before they need the room; buildings must refill on an academic schedule; financing has its own payment and maturity dates. Signed obligations can make revenue more collectible while leaving unleased beds and refinancing risk with the owner. This six-property study follows those claims without turning a small, incomplete sample into a claim about monopoly rents or realized investor returns.
Method & limits: The six-property model and lease archive use July 2026 inputs. Historical sources include SkyLoft’s 2019 underwriting and preferred-equity terms, ACC’s 2021 leasing-cycle disclosure, and UT’s posted 2026–27 rates and payment calendar; UT’s $100 application fee is confirmed in its application FAQ. Historic underwritten and annualized data are not audited current results, and posted UT rates retain their approval qualification. Other current debt, executed leases, ownership outcomes and surveillance status are not refreshed. The sample cannot establish market concentration, realized sponsor returns or a market-wide rent premium.
Compare the full term, not one installment
Individual-bed leasing generally separates one resident’s liability from another’s unpaid rent. It also prices a bundle: location, bedroom and bathroom privacy, furnishings and services, over a specified term. The useful comparison begins with the total obligation for the period the student values, followed by mandatory charges and the payment schedule. An installment is a way to divide that obligation, not a complete measure of what the room costs.
The comparison is clearest at 2400 Nueces. Its 12-month 4×4 rate has the lower advertised installment, but the nine-month contract costs $2,703 less in total and is cheaper for a student who only values the academic year. Callaway's ten-installment structure is more expensive, but it also includes food, housekeeping, utilities, internet, and furnishings. A price comparison that ignores term and service mix overstates precision.
The choice becomes less flexible once signed. The archived Torre lease requires full-term rent despite nonoccupancy and includes a reletting fee; Callaway puts the replacement burden on the resident after specified deadlines. A guarantor helps collect a tenant’s signed obligation. It does not create an obligation for a bed that nobody leased. This distinction explains how a landlord can have enforceable contracts and still face lease-up risk.
The study’s $2,703 difference is a useful decision threshold. For a student who needs only the academic year, the longer term needs at least that much additional value from summer use or net recovery before it becomes cheaper on the same service basis. Count only rent genuinely covered by a replacement resident or cash received, less incremental fees and costs. Check permission, vacancy, collection risk and any continuing legal liability separately; the full-term total already includes the resident’s contractual rent, so do not deduct that same rent again from recovery. A hoped-for replacement tenant is not cash already received.
I would compare both the total obligation and the largest near-term payment. Equal installments do not ensure evenly spaced cash needs: UT’s current billing description, for example, places the first two installments on September 1. The quoted historical study rates remain dated; a new leasing decision needs the actual offered term, mandatory charges, deposit treatment and payment calendar alongside the advertised installment.
Scroll the table to compare every column.
| Product | Advertised installment | Installments | Total including modeled fees | Effective / contracted month | Per academic-use month | Interpretation |
|---|---|---|---|---|---|---|
| 2400 Nueces 4×4, 12-month | $1,141 | 12 | $13,792 | $1,149 | $1,532 | Lower sticker; includes summer cost for a nine-month user |
| 2400 Nueces 4×4, 9-month | $1,221 | 9 | $11,089 | $1,232 | $1,232 | Higher installment; lower total obligation |
| Callaway entry private-dorm rate | $1,959 | 10 | $19,590 | $1,959 | $2,062 | Meals and service bundle included; parking and insurance extra |
| College Houses private room control | $955 | 9 | $8,595 | $955 | $955 | Lower-cost academic-term cooperative control |
Six buildings and 4,805 beds expose different capital structures
The sample was chosen for the quality of the available ownership and financing evidence. SkyLoft exposes a 2019 securitized mortgage and preferred-equity stack. 2400 Nueces records a private ground-lease development followed by a university purchase. Waterloo connects a 0.45-acre site, a density bonus, a 796-bed tower, and a sale to Global Student Accommodation. The Standard shows construction debt followed by a recapitalization. Callaway provides a service-heavy private-dorm product. 26 West supplies an older asset with a reported acquisition price.
Follow the rent collector through the capital structure. A title-holding borrower can lease the building to a related master tenant. A whole mortgage can divide into senior and subordinate notes, while preferred capital has payment and intervention rights above common equity. Those layers can let a property continue operating through a change in who controls its remaining cash. The name on the leasing office identifies only the customer-facing end of the structure.
The sample also cannot prove market concentration. At the study cutoff, American Campus Communities, part of Blackstone, and Landmark controlled multiple properties, while UT, Global Student Accommodation, and the SkyLoft borrower represent other forms of ownership. Unresolved parcel entities and bed counts make a precise concentration ratio indefensible.
Scroll the table to compare every column.
| Property | Beds | Owner / sponsor | Manager / brand | Evidence status |
|---|---|---|---|---|
| SkyLoft | 674 | NP Skyloft, DST at 2019 origination; current control unresolved | SkyLoft brand; NP Skyloft Leaseco at origination | High for 2019; incomplete currently |
| 2400 Nueces | 622 | Board of Regents of The University of Texas System | UT University Housing and Dining | High purchase evidence; asset debt allocation unresolved |
| Waterloo | 796 | Global Student Accommodation | Yugo Austin Waterloo | High sale chronology; low current debt and basis precision |
| The Standard | 934 | Landmark Properties | Landmark Properties | High sponsor evidence; recap balance and maturity undisclosed |
| Callaway | 753 | American Campus Communities / Blackstone platform | American Campus Communities | High sponsor and revenue evidence; low basis and debt precision |
| 26 West | 1,026 | American Campus Communities / Blackstone platform | American Campus Communities | High acquisition evidence; current debt unresolved |
Study map / six-property evidence sample
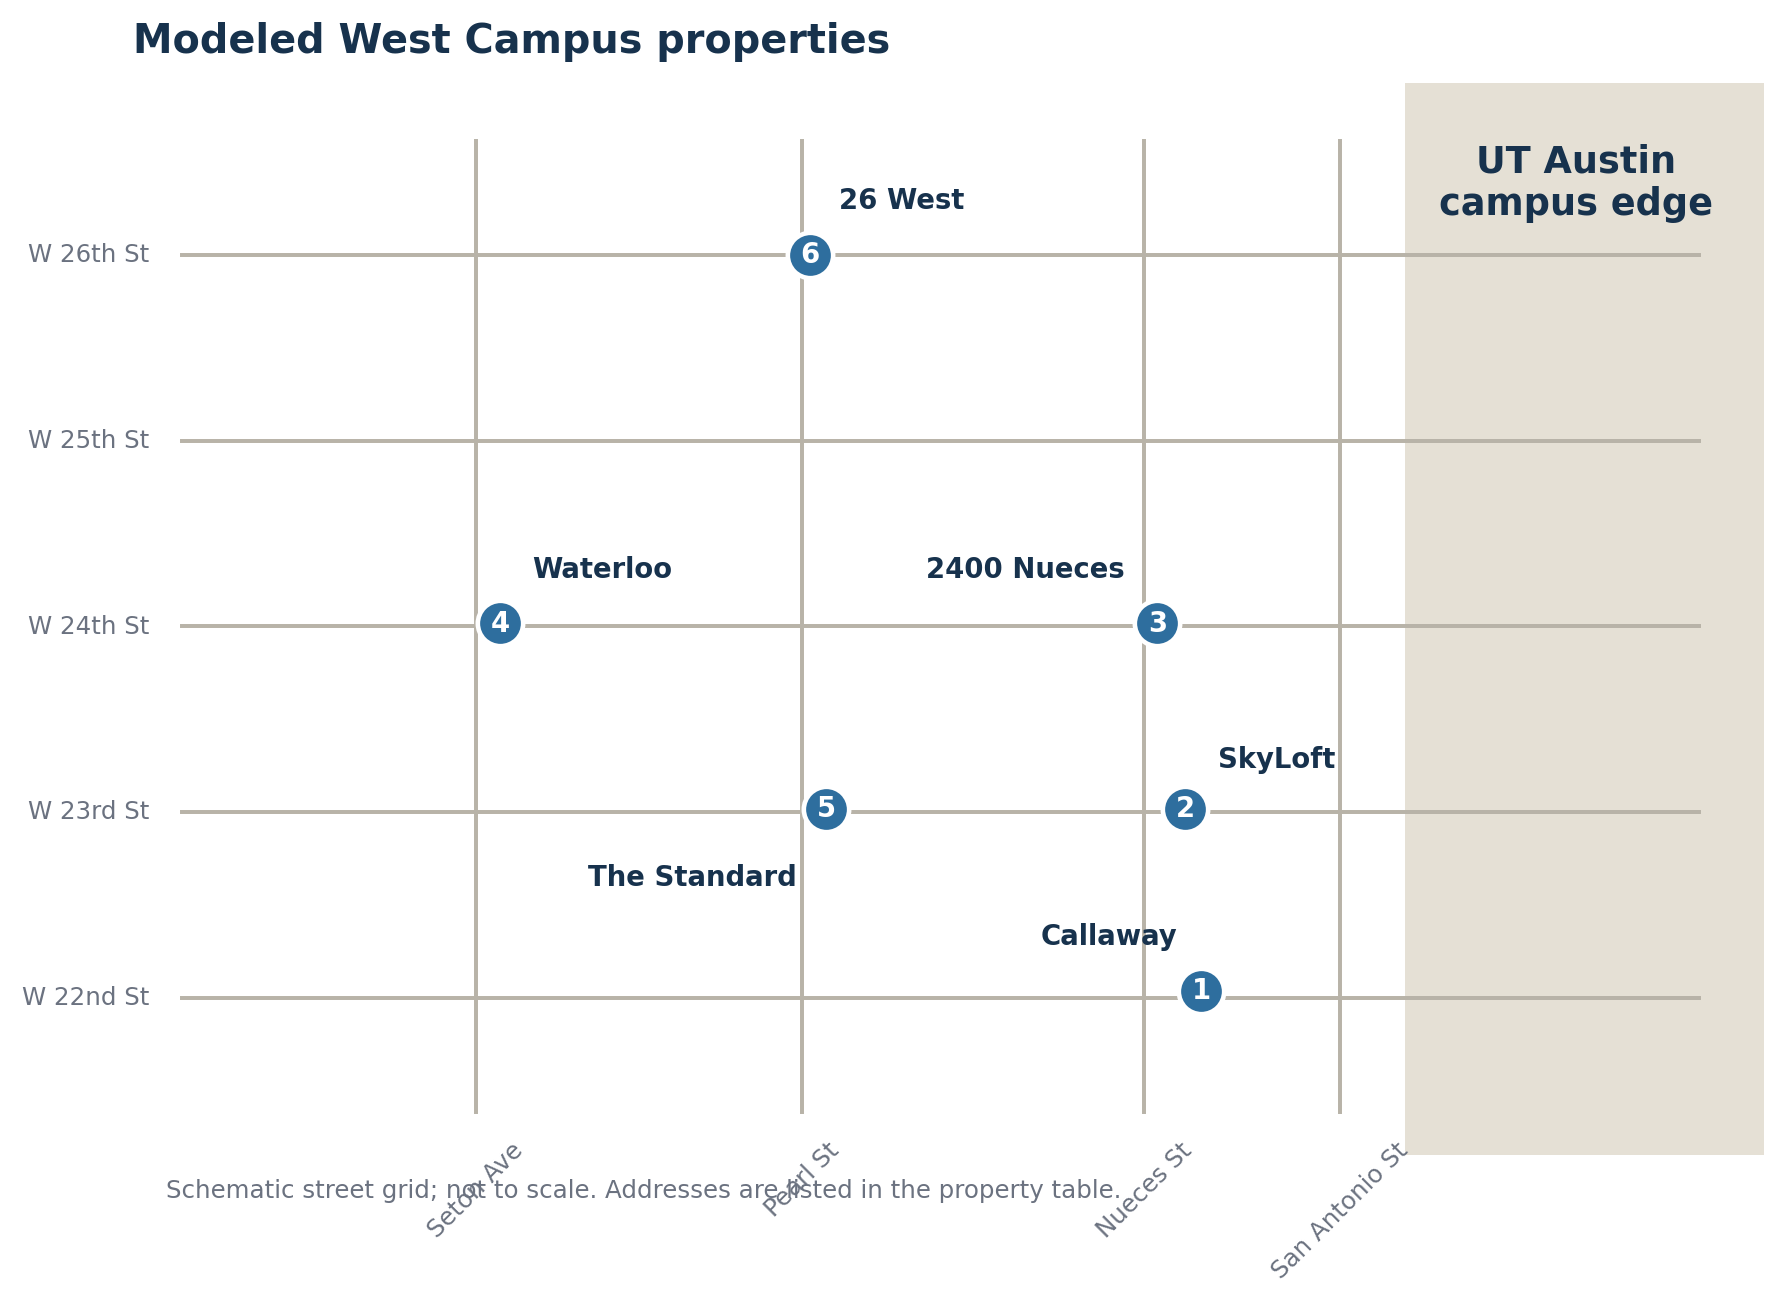
NOI stops before the owner’s financing costs
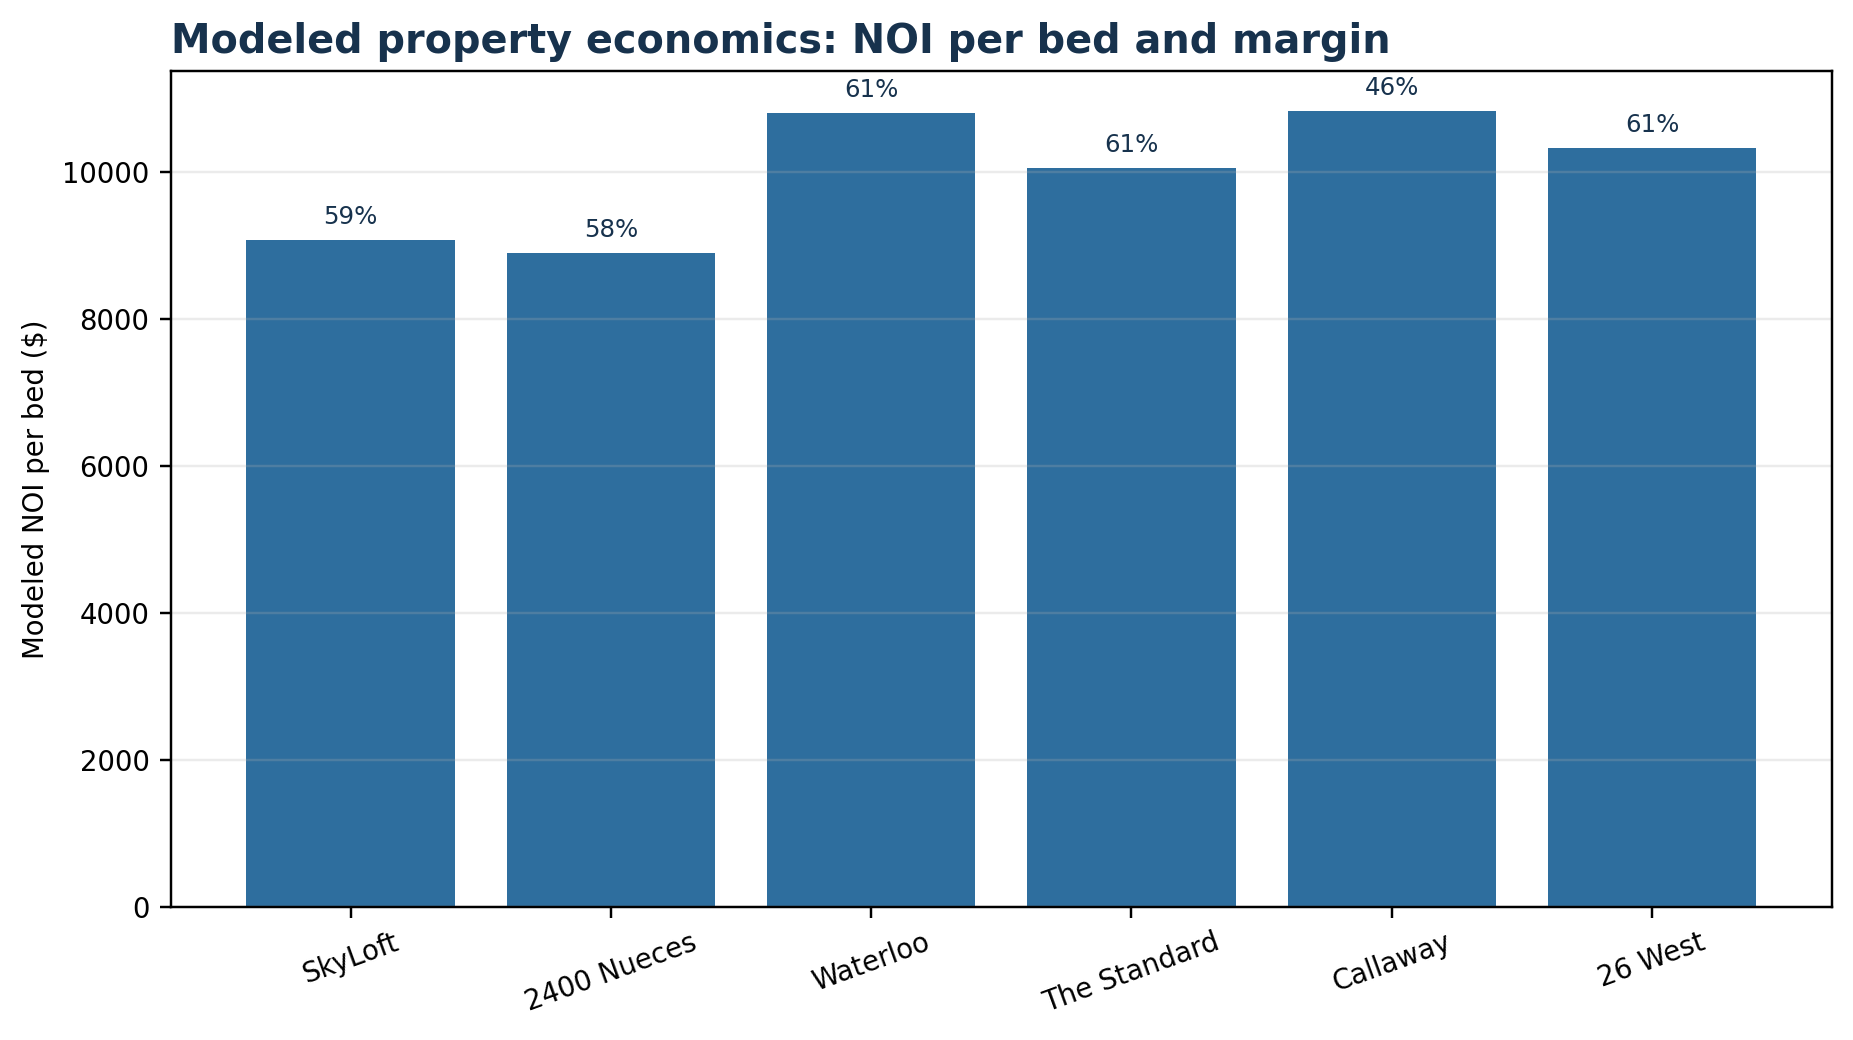
The normalized workbook deducts unleased beds, bad debt and concessions from face rent, adds ancillary income and subtracts property operating costs to reach NOI. Replacement reserves are deducted below NOI in the cash-flow waterfall. Its property results are scenarios. SkyLoft’s 2019 term sheet provides the clearest historical operating evidence, including four months of 2018 results annualized and a January 2019 underwritten rent roll. That is narrower than an audited 2019 operating statement. The six modeled cases use public physical data, asking rates and declared expense assumptions at the July cutoff. Historical underwriting.
Five properties produce modeled NOI margins between 58.4% and 61.5%. Callaway produces 46.0% because food, housekeeping, utilities, payroll, and contracted services lift expense per bed to roughly $12,725, versus about $6,300 to $6,800 at the other properties. The student-facing price is highest there, but a smaller share becomes property NOI.
The gap widens below NOI. Debt service, preferred returns, replacement reserves, refinancing constraints, taxes at ownership entities, and nonrecurring capital separate property performance from common-equity performance. The modeled levered IRRs span from negative 10.3% at SkyLoft to 25.5% at 26 West. Those are normalized scenarios, not realized sponsor statements.
Scroll the table to compare every column.
| Property | Effective gross income | NOI | NOI margin | Modeled levered IRR | Combined-stress refi paydown | Capital-structure boundary |
|---|---|---|---|---|---|---|
| SkyLoft | $10.35M | $6.12M | 59.1% | –10.3% | $38.1M | 2019 whole loan and preferred stack disclosed |
| 2400 Nueces | $9.48M | $5.54M | 58.4% | 17.6% | $7.8M | Actual purchase; debt allocation illustrative |
| Waterloo | $13.99M | $8.60M | 61.5% | 8.3% | $41.6M | Owner known; current debt illustrative |
| The Standard | $15.44M | $9.39M | 60.8% | 10.6% | $46.3M | Recap known; current balance illustrative |
| Callaway | $17.74M | $8.15M | 46.0% | 13.0% | $26.3M | Platform ownership known; debt and basis illustrative |
| 26 West | $17.24M | $10.60M | 61.4% | 25.5% | $0.0M | Actual 2011 purchase; current debt illustrative |
Figure 01 / property economics
SkyLoft’s preferred claim leaves little for common equity
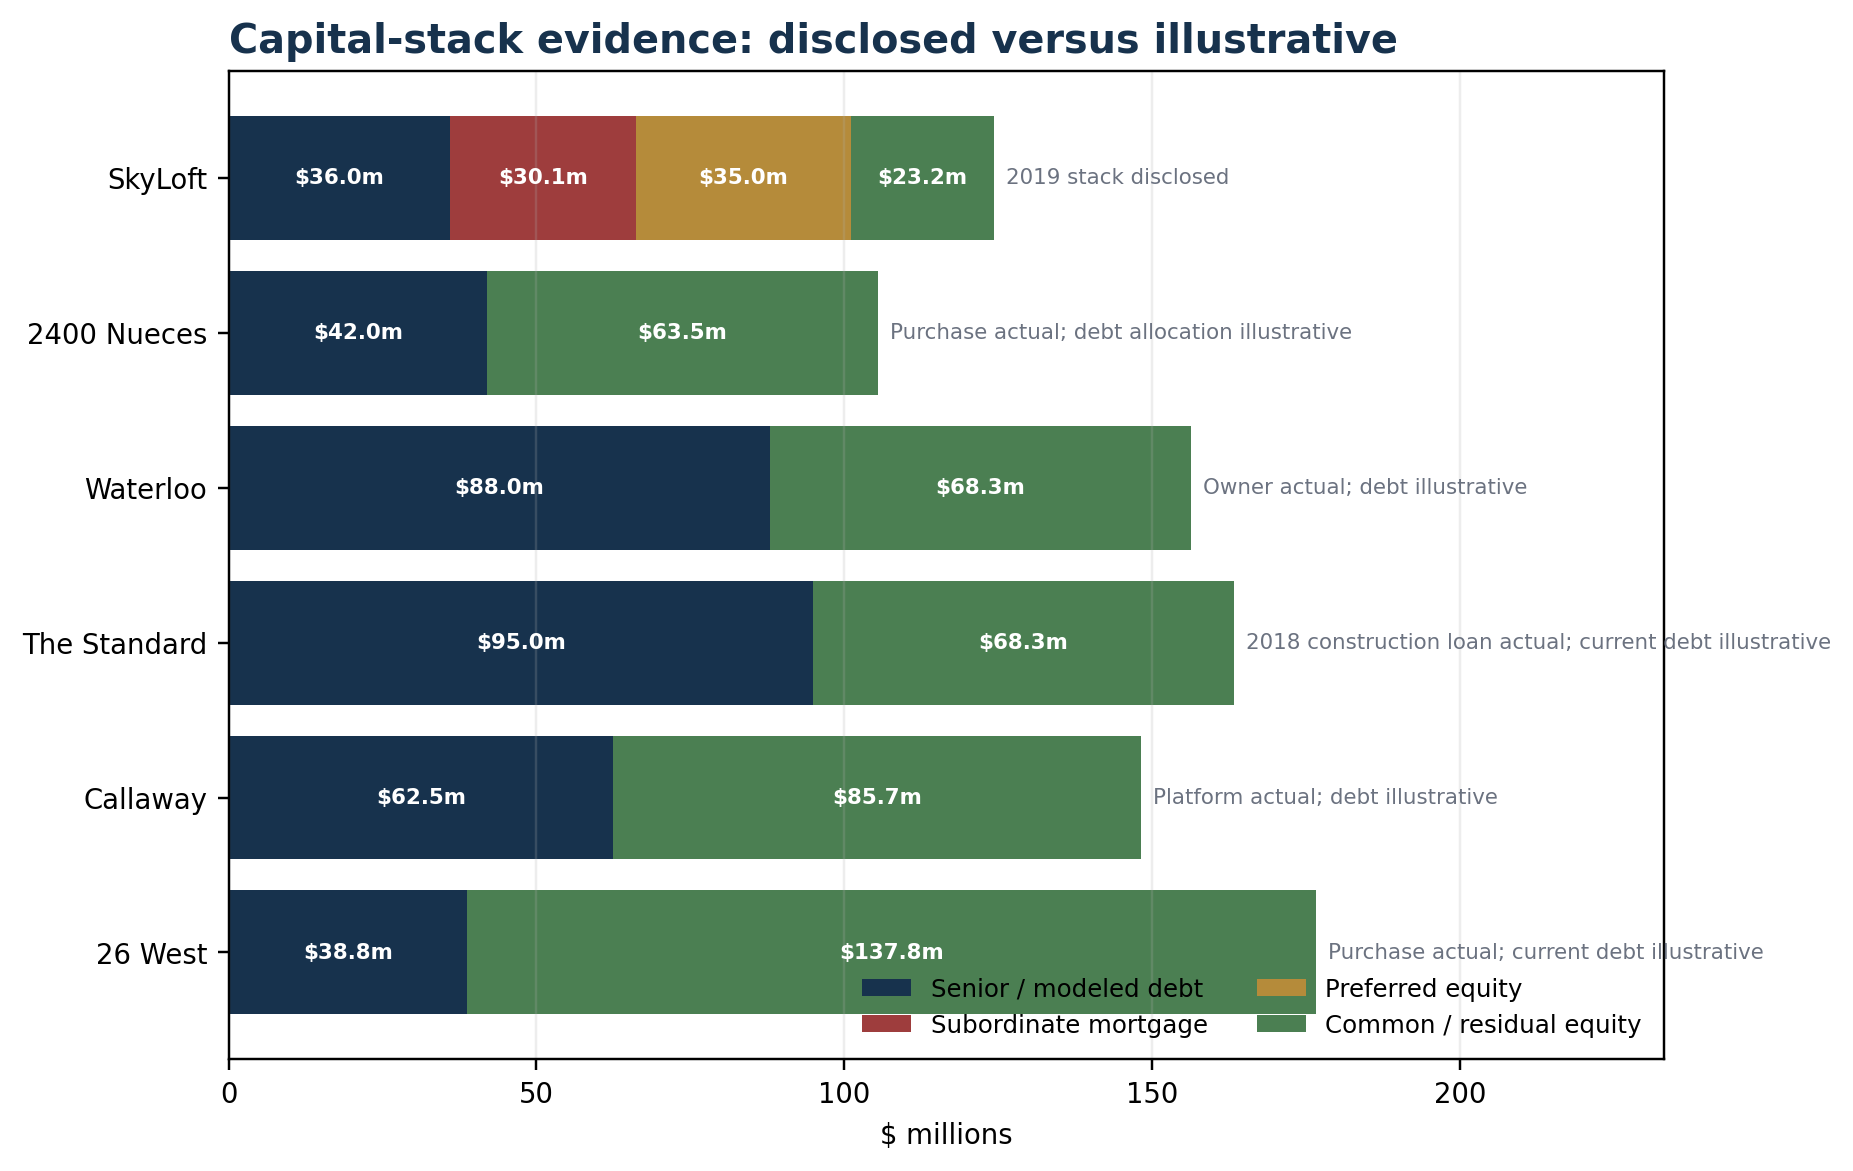
NP Skyloft, DST acquired the 212-unit, 674-bed tower for $119.55 million. Disclosed uses, including reserves and closing costs, totaled about $124.37 million. A $66.125 million whole mortgage sat above the property: $36 million of senior notes and a $30.125 million subordinate companion note. A $35 million preferred-equity position sat above common sponsor capital.
The preferred position earns a 14% return under the historical terms: 8% current pay and 6% accrued. Its initial term is 12 months, alongside a ten-year mortgage, and the recognition agreement provides conditional control and loan-purchase rights. The contract dates matter as much as the nominal ranking. A claim called equity can demand cash or influence control well before the property mortgage matures. These are 2019 disclosed terms, not proof that the same claim remains outstanding today. Preferred-equity terms.
At normalized NOI of $6.12 million, whole-loan interest consumes about $2.94 million, preferred current pay consumes $2.8 million, and replacement reserves consume about $202,000. Approximately $171,000 remains for common equity before ownership-level costs and taxes. The central modeled value of $87.4 million covers the mortgage but not the mortgage plus preferred principal. In this modeled case, common equity is out of the money and the preferred layer is impaired before accrued return.
Fitch reported special servicing in March 2024 and 42% occupancy in March 2025. An active leasing page does not resolve that capital distress: operations can continue while control and recovery claims change.
Scroll the table to compare every column.
| Layer | Amount | Economic position | Key term or right |
|---|---|---|---|
| Senior mortgage notes | $36.0M | Last property debt layer to lose value | Part of 120-month interest-only whole loan |
| Subordinate companion note | $30.125M | Impaired after junior capital and before senior notes | Part of the same $66.125M whole loan |
| Preferred equity | $35.0M | Ahead of common economically | 14% return; control and loan-purchase rights |
| Implied common sponsor capital | $23.24M | First capital layer to lose residual value | Derived from disclosed total uses |
Figure 02 / disclosed versus illustrative capital
University ownership and development entitlement change the model
2400 Nueces is a useful control precisely because it is not a clean private-market comparable. The UT System bought the leasehold estate and improvements for $74.759 million in 2018. University ownership changes taxes, governance, lease terms, and the required guarantor. The model assumes no property-tax expense and produces $5.54 million of NOI. Its 17.6% modeled levered IRR depends on an illustrative bond allocation, so the purchase price is established while the asset-level financing is not.
The university’s published nine- and 12-month options show why term matters. A higher nine-month installment can still cost less over the academic year. Proximity alone does not require a full-year private-tower commitment.
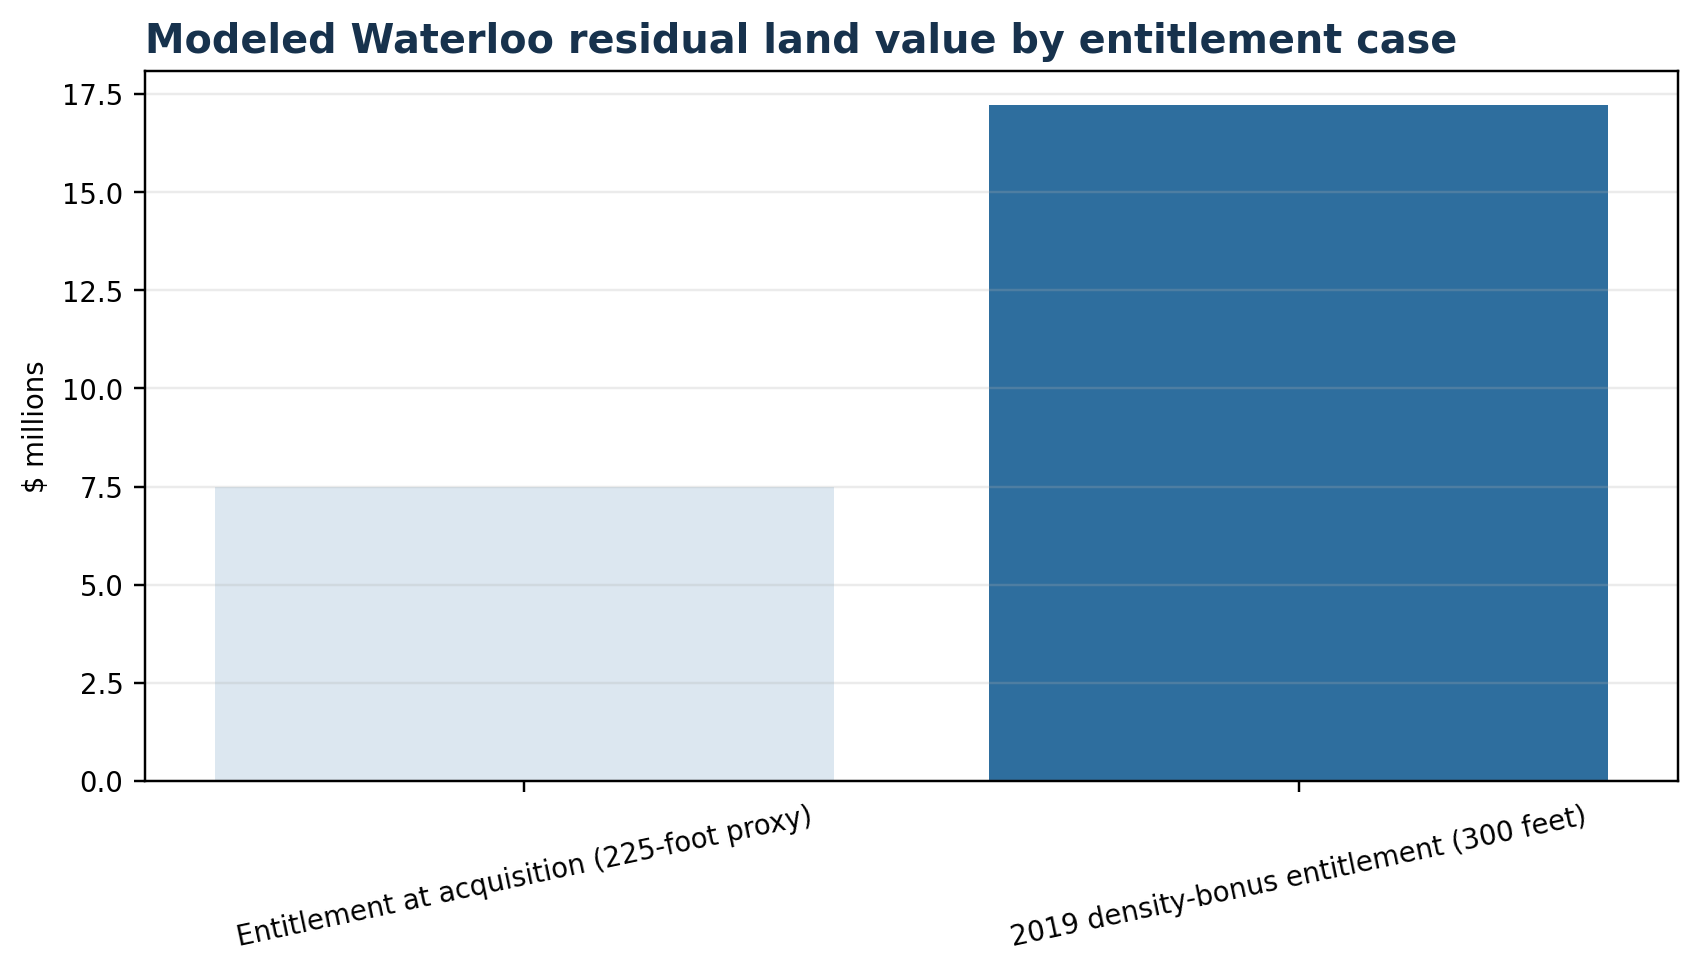
Waterloo turns land-use entitlement into a development calculation. LV Collective acquired a 0.45-acre site, used a November 2019 density-bonus amendment to support a 300-foot, 796-bed tower with an affordable set-aside, delivered it in 2022, and sold it to Global Student Accommodation. The sale price and full budget were not disclosed, so the workbook reconstructs a central $155 million development cost rather than presenting one invented transaction number.
The development case assumes $9.5 million of stabilized NOI, distinct from the $8.60 million normalized operating case in the property tables. The operating model calculates $8,596,148 from $13,985,720 of effective gross income less $5,389,572 of expenses. The development model instead imposes $9.5 million as a separate stabilized assumption, about $0.90 million higher; it does not report an observed improvement. At that development assumption, the central yield on cost is 6.13%. A 5.50% exit cap implies $172.7 million of value and $17.7 million of development profit. That 63-basis-point spread is thin: a 50-basis-point exit-cap increase cuts profit to $3.3 million, one month of effective concessions makes it slightly negative, and the combined cost, leasing, and exit shock produces a modeled $43.6 million loss.
Figure 03 / Waterloo development stress
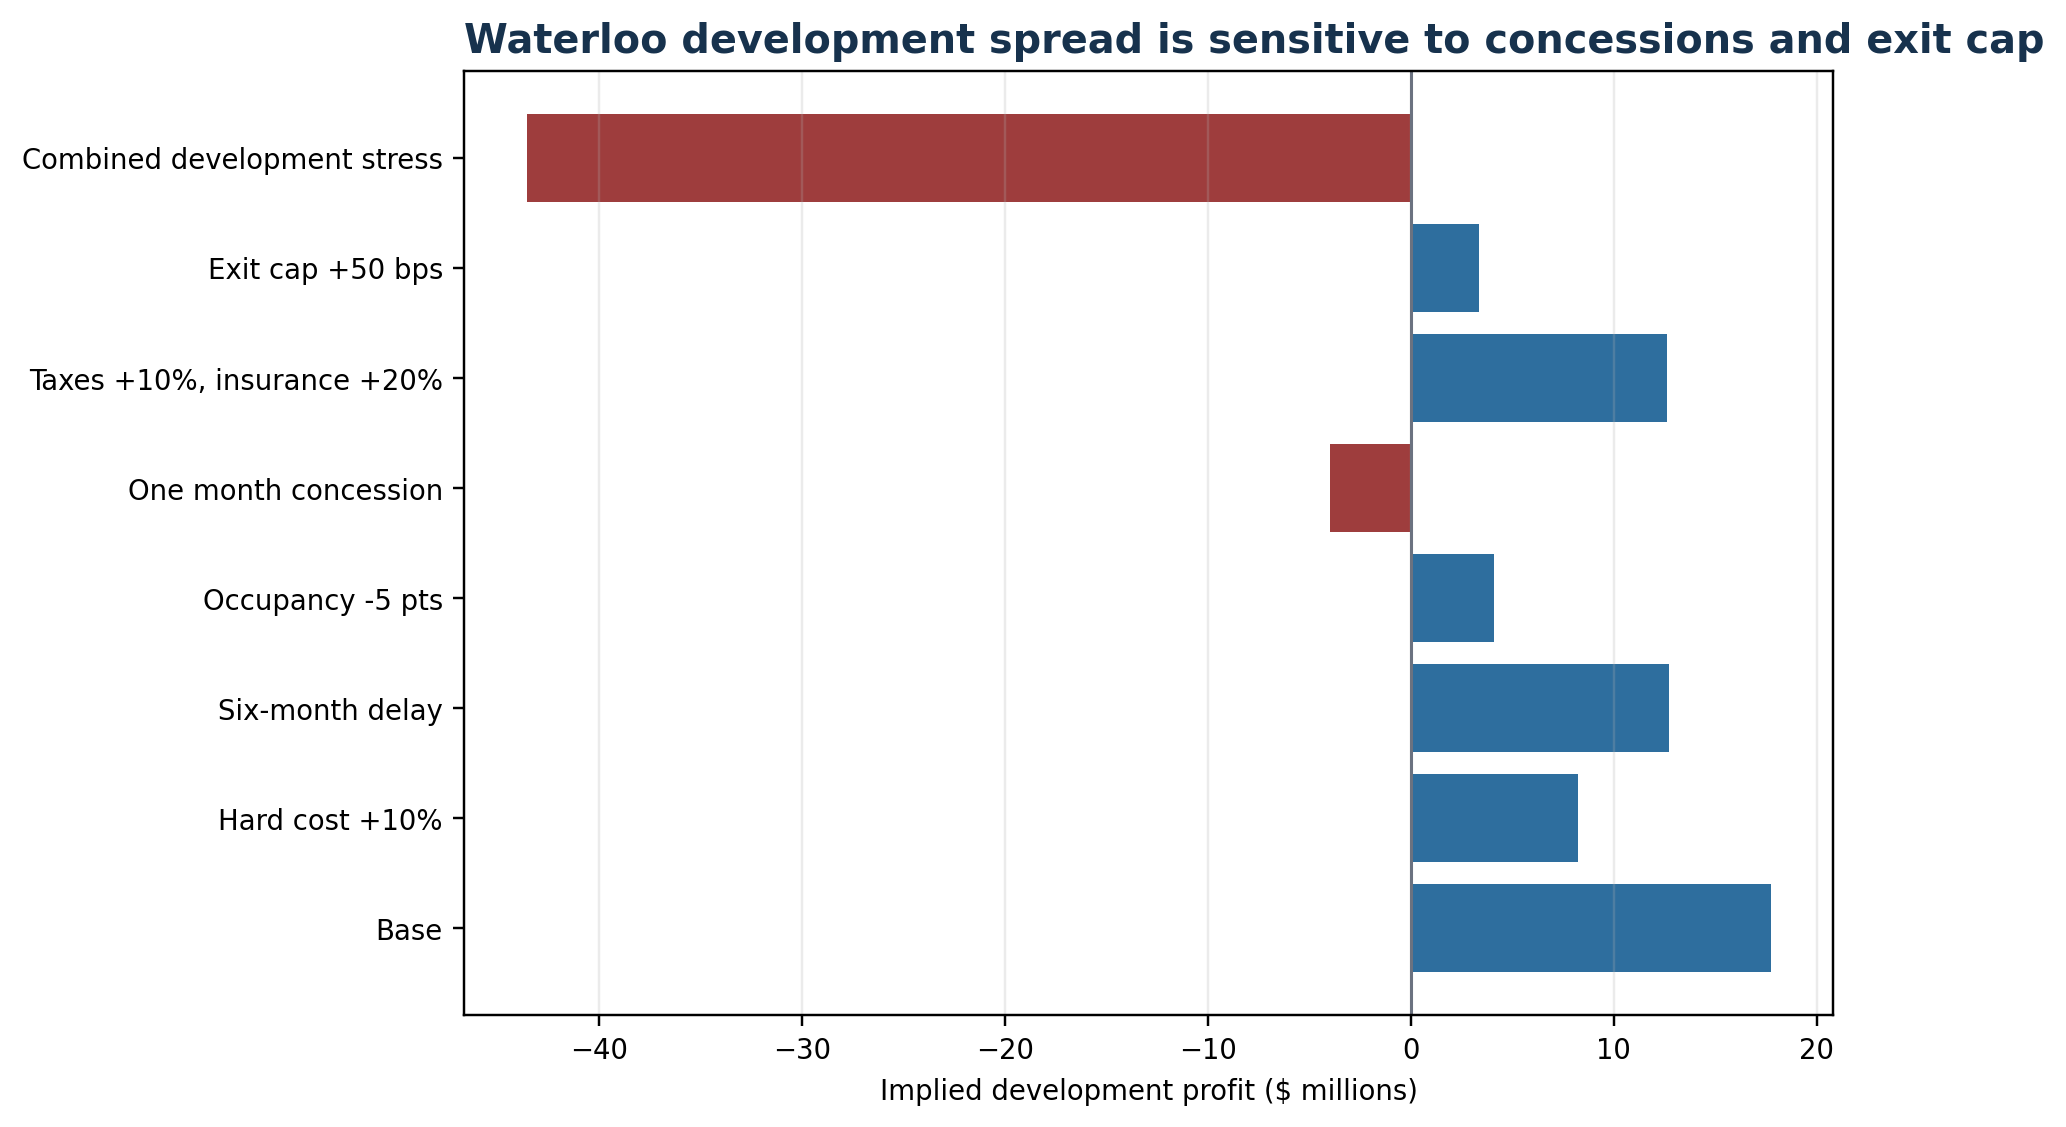
Figure 04 / entitlement value
Basis separates The Standard, Callaway, and 26 West
The Standard shows how a high-margin tower can sit close to a financing threshold. Landmark completed the 934-bed property after a reported $101.1 million construction loan and retained ownership in a 2023 recapitalization. The recap balance, rate, and maturity were not disclosed, so the workbook uses a $95 million illustrative balance at the study cutoff. Under the combined stress, the model requires the largest paydown in the sample: $46.3 million.
Callaway reaches similar NOI with a different statement. Its $17.74 million of effective gross income is the sample high, but $9.58 million of expense leaves $8.15 million of NOI. At an illustrative central basis and 50% leverage, the ten-year common IRR is 13.0%. A student can face an expensive, difficult-to-exit contract while the owner earns an ordinary modeled return for a service-heavy asset. Both can be true.
26 West is the low-basis case. American Campus Communities bought the 1,026-bed property for $86.2 million in 2011. The study’s normalized statement produces $10.60 million of NOI and a central value of $176.6 million. Its 25.5% modeled levered IRR is the sample high because the acquisition basis is far below the study’s replacement economics. It is not a realized sponsor return: debt at the study cutoff, major capital improvements, capital calls, and historical distributions remain unresolved.
- The Standard: strong operations can still face a large refinancing gap if recapitalization debt is high.
- Callaway: the highest student-facing bundle also carries the largest modeled operating cost per bed.
- 26 West: the oldest reported acquisition basis preserves the largest modeled equity cushion.
- Rent practices alone do not rank owner returns.
The building has to win its lease-up again
The student’s desire for a room near campus gives the product value, but it does not eliminate annual competition. American Campus Communities’2021 report describes a concentrated season in which properties must be re-leased each year. It distinguishes the 12-installment off-campus model from residence halls with ten installments and weaker summer cash flow. Longer contracts stabilize receipts across a year; they do not remove the next annual leasing decision. Historical operating model.
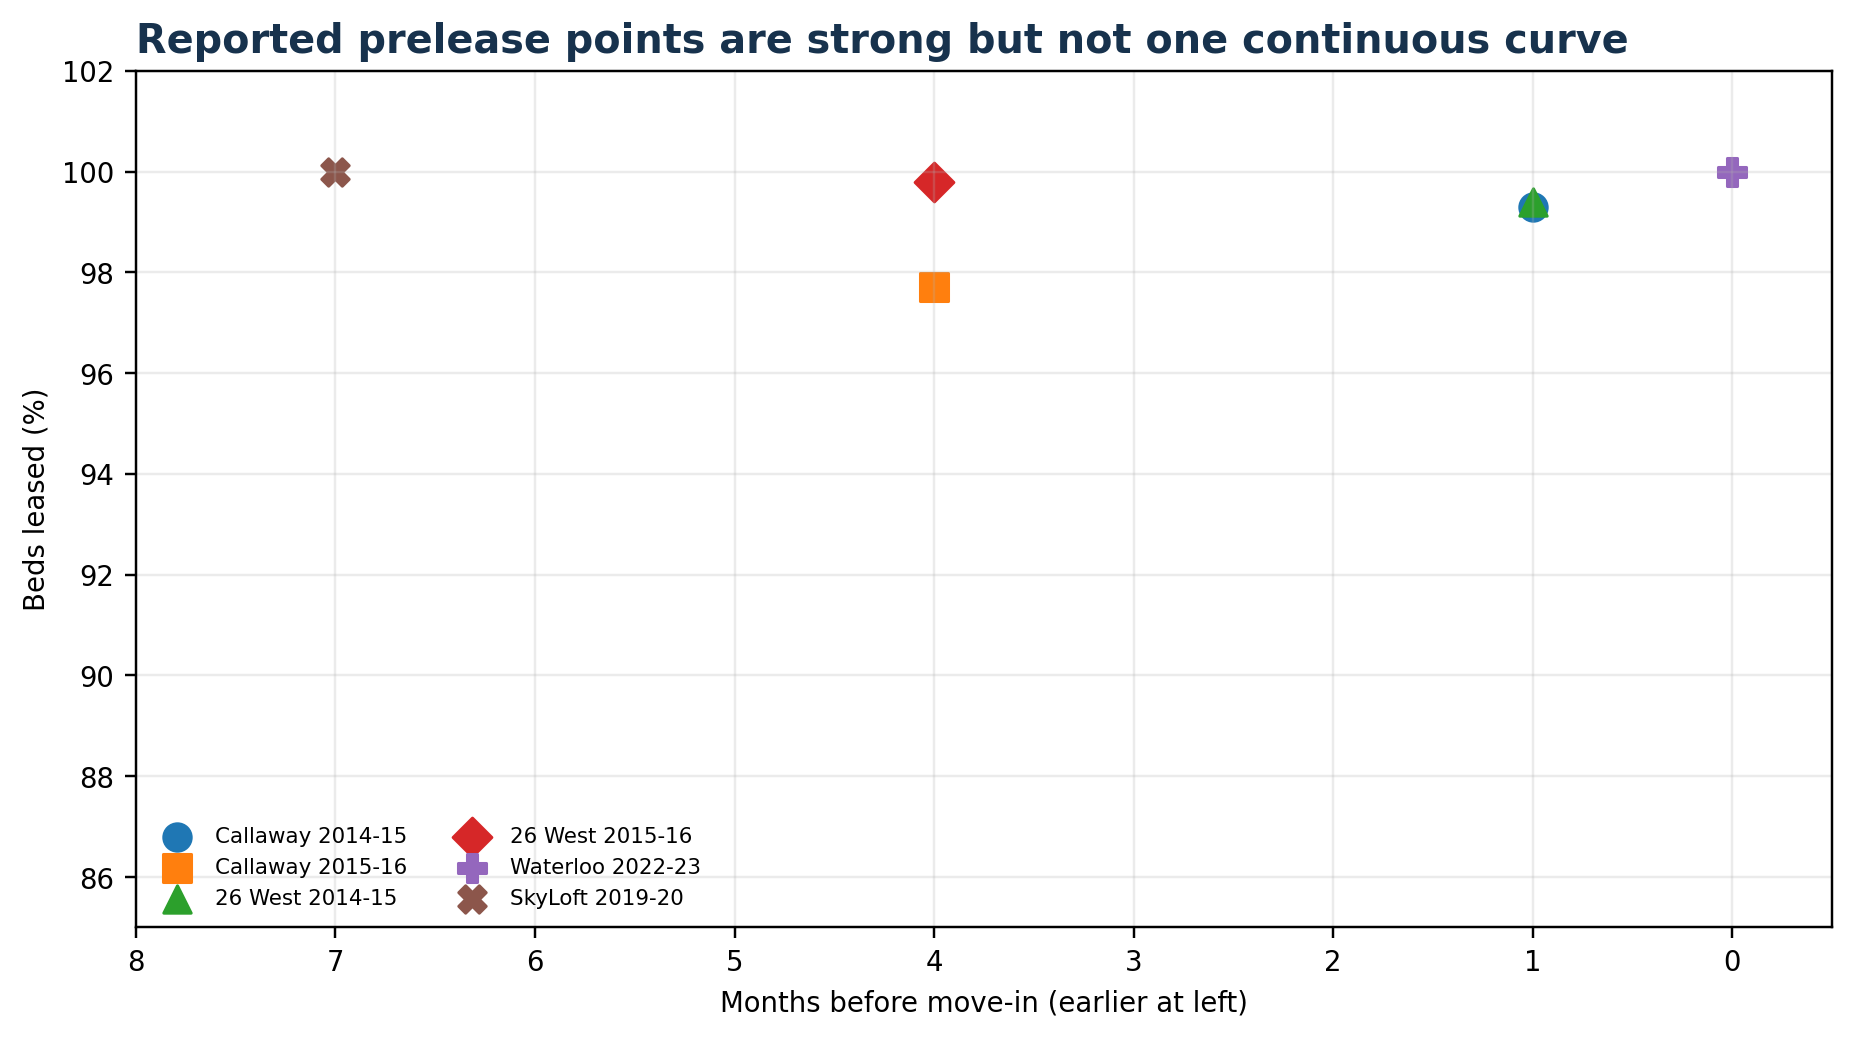
Preleasing is therefore valuable evidence when it records executed commitments for a particular academic year. Its economic quality depends on price, concessions, cancellation rights and collectibility. SkyLoft’s 2019 underwriting illustrates the distinction: a 100%-leased rent roll sits alongside an economic vacancy assumption. A leased-bed count and expected rent collection answer different questions. The later 42% occupancy observation belongs to March 2025, not the same cohort or a continuous lease-up curve. Underwriting; dated surveillance.
The strongest case for the sector is that a large university supplies a recurring pool of potential residents and walking proximity cannot be manufactured cheaply at another address. Individual-bed leases, furnishings and amenities can make the product useful. The underwriting still needs a complete supply/pipeline denominator and the share of students able and willing to pay for each product.
The model’s premium decomposition starts with an $850 conventional split-housing control and assigns value to location, services, new construction and privacy. About $100 per month remains unexplained centrally. Those assumptions are broad and are not a hedonic regression. The residual cannot be relabeled market power. Likewise, urgency and advertised concessions at Rise, Rambler and The Standard do not reveal the number of beds left.
The bargaining position changes after a student signs. Full-term liability and costly relets can make an unwanted lease difficult to escape even while another building is offering a concession. The evidence for that contract-level lock-in is stronger than the evidence for a market-wide monopoly. A student can use the former finding now; establishing the latter would require different data.
Figure 05 / reported prelease points
Positive NOI can coexist with a refinancing shortfall
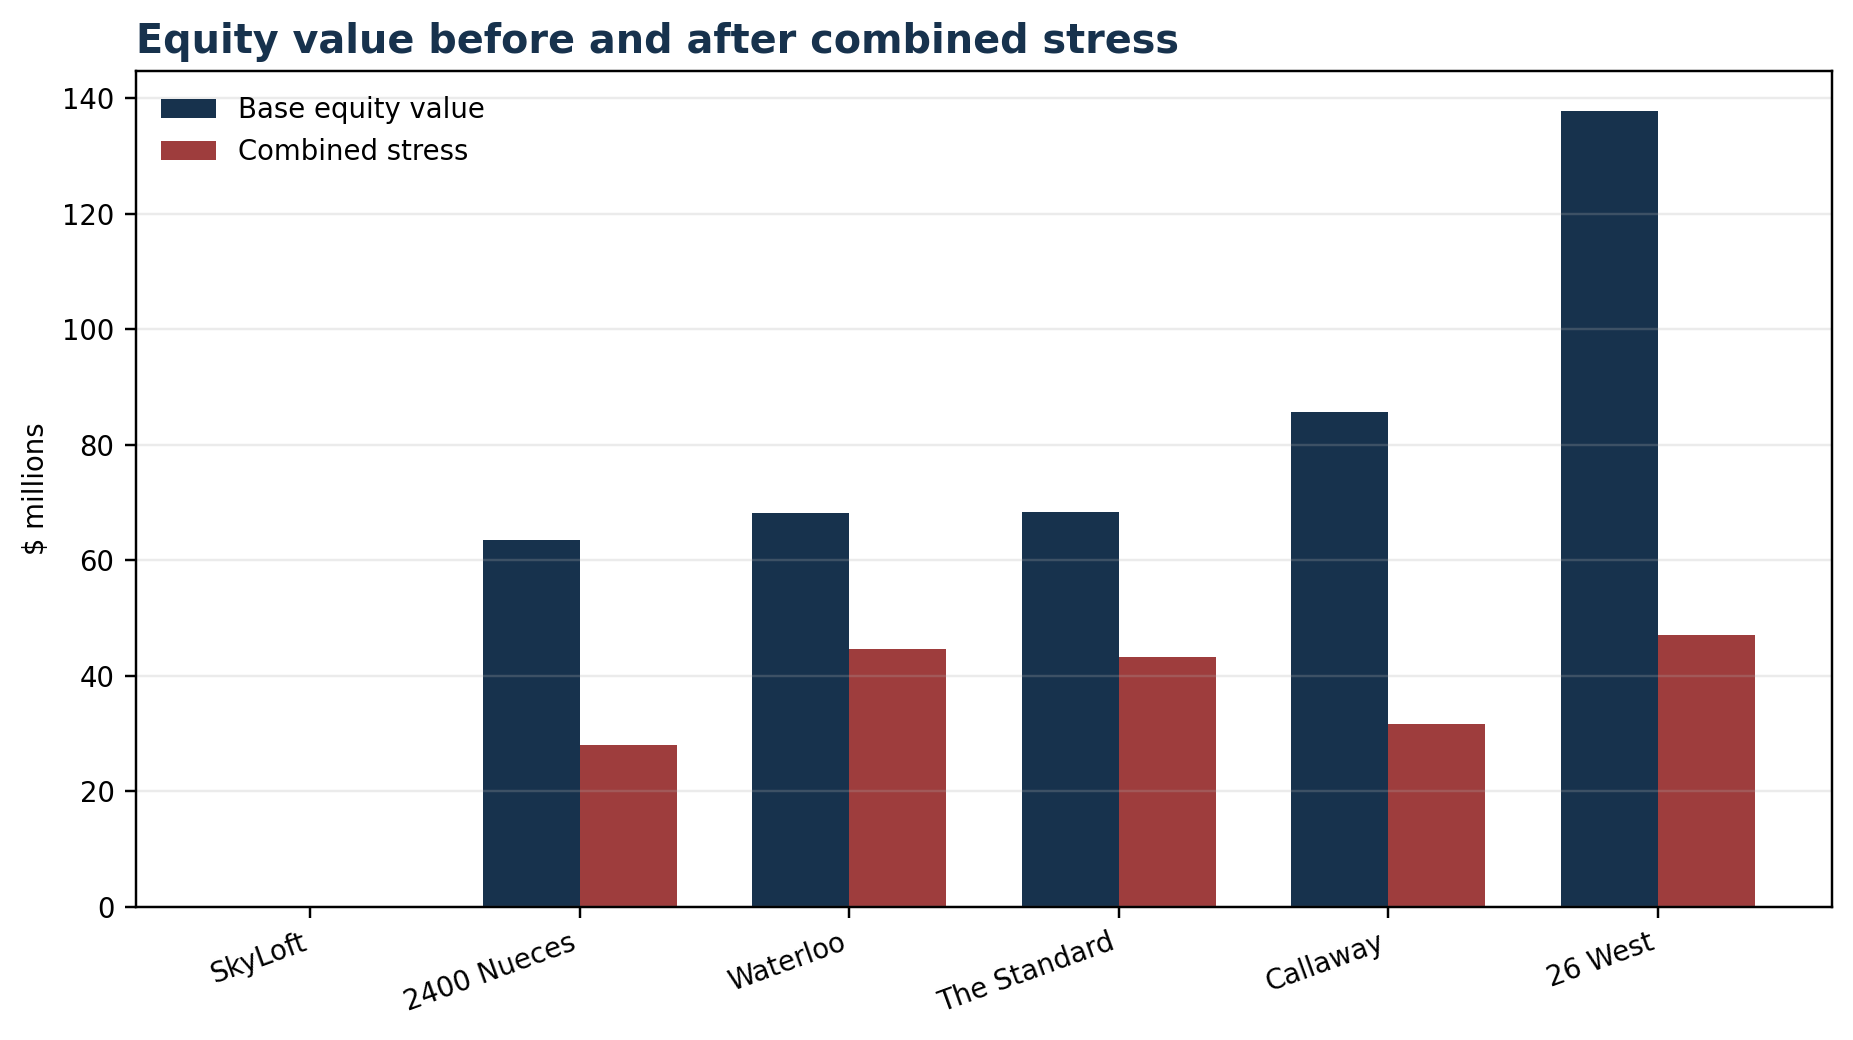
The combined model applies a 4% rent cut, seven points of occupancy loss, one additional month of concessions, 10% higher taxes, 20% higher insurance, 8% higher payroll and repairs, $500 per bed of replacement spending, a 75-basis-point cap-rate increase, and refinancing 200 basis points above the base rate. It is intentionally severe and internally linked, but it is not a forecast of West Campus.
SkyLoft begins with the least common-equity protection. NOI falls from $6.12 million to $3.94 million, cash flow to common turns negative, and implied value falls to $50.9 million—below the $66.125 million whole mortgage. Common and preferred capital are wiped in the model, and part of the subordinate note lacks value coverage.
The Standard, Waterloo and Callaway keep positive property NOI in the combined stress but need large modeled refinancing paydowns. A building can remain useful and cash-producing while a replacement lender will advance less than the balance coming due. That gap is a dated funding requirement, potentially met by new equity, preferred capital, an extension or a sale. A positive NOI headline does not identify who can supply that money or at what cost.
Scroll the table to compare every column.
| Property | Base NOI | Combined-stress value | Modeled refi paydown | Interpretation |
|---|---|---|---|---|
| SkyLoft | $6.12M | $50.9M | $38.1M | Value falls below disclosed whole mortgage |
| 2400 Nueces | $5.54M | $62.3M | $7.8M | Uses illustrative bond allocation; public support differs |
| Waterloo | $8.60M | $91.1M | $41.6M | Positive NOI does not preserve old illustrative balance |
| The Standard | $9.39M | $91.9M | $46.3M | Largest modeled paydown in sample |
| Callaway | $8.15M | $67.9M | $26.3M | Service-heavy expense base amplifies stress |
| 26 West | $10.60M | $104.7M | $0.0M | Lower modeled leverage preserves refinance room |
Figure 06 / equity under stress
Vacancy reaches sponsor equity before senior property debt
A tenant or guarantor owes the signed lease; neither covers the building’s other vacant beds. Unleased inventory reduces cash through lost rent and concessions, and common equity bears that reduction first through distributions and value. When many leases turn over on the same calendar, an apparently small miss in one leasing season can persist through much of the financing year.
Preferred equity follows economically, although contractual control can move before the preferred principal is fully lost. Mezzanine and subordinate mortgage debt follow according to their documents. Senior mortgage debt is last at the property level. Reserves, enforcement costs, guarantees, and claim timing can alter recovery, but the order is set by contracts rather than the consumer brand.
At SkyLoft's central modeled value of $87.4 million, the whole mortgage remains covered while common equity is zero and the $35 million preferred principal is partly impaired. At the $50.9 million combined-stress value, common and preferred capital are gone and roughly $15.2 million of the subordinate mortgage lacks value coverage, while the $36 million senior balance remains covered.
- Signed tenant or guarantor: liable only for the executed lease, not speculative vacancy.
- Property operating cash flow: first place where vacancy, bad debt, and concessions appear.
- Common sponsor equity: first capital layer to lose residual value.
- Preferred equity: next economic loss layer, often with earlier intervention rights.
- Mezzanine or subordinate mortgage debt: impaired after junior capital according to contract priority.
- Senior mortgage: last property-level claim to absorb the remaining shortfall.
Missing debt and lease records limit the conclusions
Property-level debt, rates, maturities, guarantees and reserves at the study cutoff remain unresolved for five of the six properties. Waterloo's sale price and full development budget are undisclosed. Property-level executed leases, bad-debt histories, remaining inventory and realized concessions are unavailable.
Those gaps prevent a clean concentration ratio, a market-wide rent regression, a realized sponsor-return comparison, and a definitive ranking of refinancing risk. Filling them would require deed and UCC work, lender or sponsor disclosure, weekly lease-up files, executed-lease samples, property-level operating statements, and a complete bed and pipeline denominator.
The supported result is a set of distinct bargains. Students pay for proximity and a service bundle, then accept a defined term and exit cost. Owners invest at different bases and must win the leasing cycle repeatedly. Capital providers receive different payment dates and control rights. Expensive rent cannot establish excessive owner returns; distressed common equity cannot establish that a student’s contract is fair. Each claim needs the part of the structure that can actually answer it.
- Do not report a market concentration ratio from this six-property evidence sample.
- Do not present illustrative non-SkyLoft debt as current reported borrowing.
- Do not treat normalized or stress-case IRRs as realized sponsor returns.
- Do not assign the unexplained rent premium to market power without executed-lease and inventory evidence.
- Do not treat a guarantor as protection against beds that were never leased.
Compare the lease first, then the capital stack
A student’s exit options depend on the signed term, guaranty, cancellation rules, and relet process. The owner’s outcome depends on costs, basis, financing, concessions, and refinancing. The six-property model keeps those questions separate rather than inferring monopoly or realized returns from rent alone.
Sources & dates
- SkyLoft UBS 2019-C16 collateral term sheet — SEC
- Fitch surveillance for UBS 2019-C16
- 2400 Nueces rates — UT University Housing and Dining
- UT System Board of Regents meeting minutes — July 11, 2018
- Waterloo development case study — LV Collective
- Waterloo acquisition report — REBusinessOnline
- The Standard recapitalization — TSB Capital Advisors
- American Campus Communities 2021 Form 10-K — SEC
- 26 West property and current pricing — American Campus Communities
- University Neighborhood Overlay Program — City of Austin
- American Campus Communities 2021 Annual Report, student-housing leasing risk
American Campus Communities · 2021 fiscal year
Verified 2026-10-25Primary annual report, mirrored PDF, physical page 16/printed 9. Describes concentrated annual re-leasing and 12-versus 10-installment structures. Historical portfolio evidence, not a current Austin lease-up observation.
- UT University Housing and Dining — 2400 Nueces application process and $100 feeVerified 2026-10-26
Application Step 3 lists the non-refundable $100 application fee. The separately credited $500 prepayment is not an additional modeled housing cost.
Supporting material
- Full investigative report
The complete 16-page article, exhibits, source notes, and assumption boundaries.
- Editable investigative report
Editable version of the six-property investigation, including lease comparisons, financing scenarios and sources.
- Executive analytical memo
A concise decision memo separating supported findings, model outputs, and unresolved evidence.
- Six-property financial model
The 17-sheet model covering sources, assumptions, property statements, scenarios, student cost, zoning, and loss allocation.
- Dossiers, methodology, and claims
Property dossiers, source ledger, claims matrix, counter-evidence, and methodology notes.